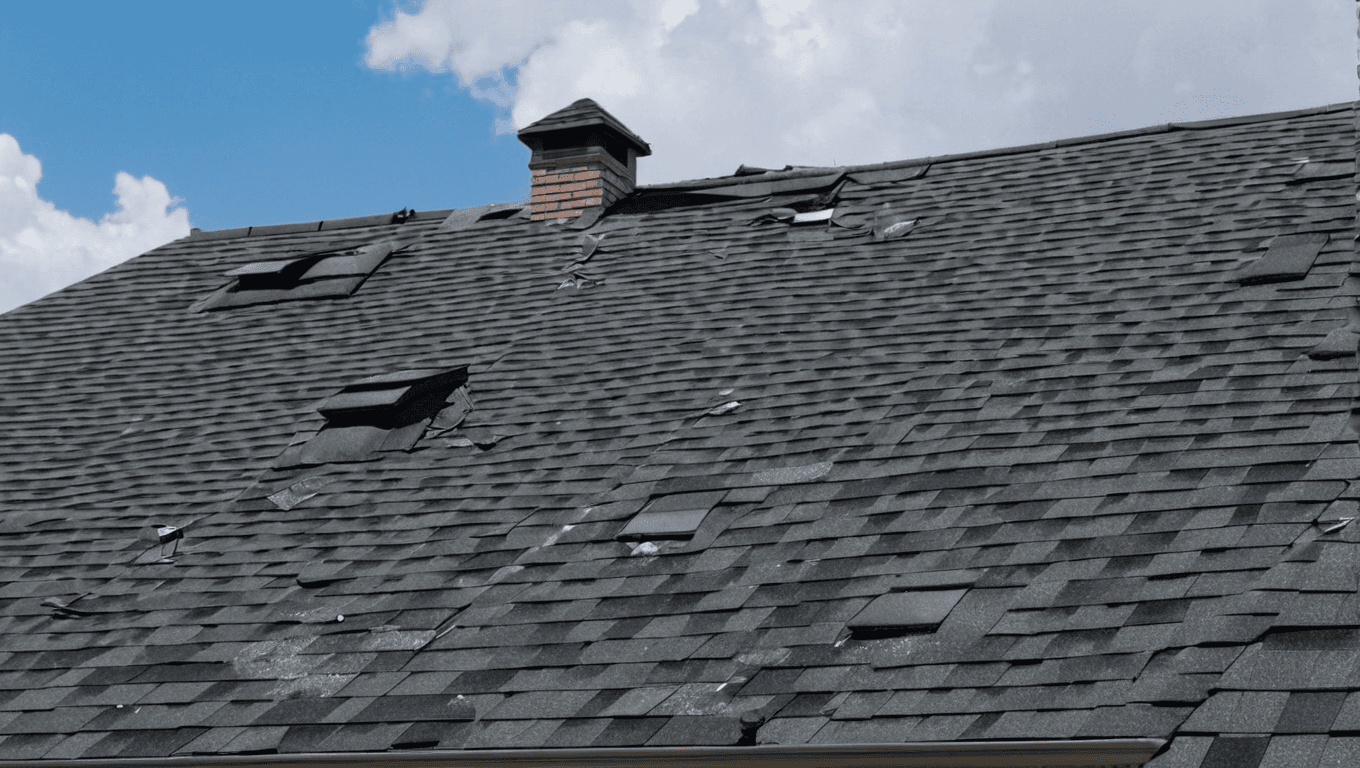
Homeowner guide — general guidance, not a report of a current local event.
Mistake 1: assuming you have one deductible
The Texas Department of Insurance (TDI) notes you might have different deductibles for each type of coverage, and a different deductible for windstorm damage. Check which one applies to hail before you budget for repairs.
Mistake 2: not asking about depreciation
TDI explains that actual cash value (ACV) coverage pays replacement cost minus depreciation, while replacement cost (RCV) coverage pays to repair or replace at current prices. If your estimate shows depreciation, ask your insurer in writing how it was calculated and whether any of it is paid after repairs are complete.
Mistake 3: not using your dispute options
- Appraisal, if your policy includes it. Each side hires an appraiser and the appraisers choose an umpire; you pay your appraiser and half of the umpire.
- A complaint to TDI at 800-252-3439 if you think you were treated unfairly.
- A public adjuster, who charges a fee. Your roofer can't fill this role on work it is doing.
- Mediation or a lawsuit. For disaster damage, give the company written notice at least 61 days before suing.
More for Dallas homeowners: Dallas storm and insurance help and our ACV vs RCV guide.
Sources
- Texas Department of Insurance: Homeowners insurance guide
- Texas Department of Insurance: What is windstorm insurance?
- Texas Department of Insurance: If you disagree with your insurer
- Texas Department of Insurance: Roofing and insurance, know the law
Reviewed September 29, 2026 against the official sources listed above. This is general information, not legal advice. Your policy wording decides what your insurer pays.
Share this article
Dallas Homeowner? Get Free Help.
Texas Property Help connects homeowners with local contractors and free insurance claim guidance — no pressure, no obligation. Texas issues no state roofing license; matching depends on availability.
Request Help Now →